PolyPid (NASDAQ: PYPD) is less than three weeks from a potentially transformative FDA decision. Its shares closed November 6 at $6.14, valuing the company at approximately $124.7 million. November 28 is the FDA’s target decision date for D-PLEX100, its candidate for preventing surgical-site infections after colorectal surgery with large incisions. Oppenheimer initiated coverage on October 27 with an Outperform rating and a $10 price target.
The approaching decision creates a timely question: does a valuation centered on that first product adequately capture what PolyPid could become? Its October 28 investor day outlined a company with a U.S. commercial partner preparing for launch, European rights available for a new deal, and a second pipeline product targeting a serious complication of diabetes.
A favorable FDA outcome could move PolyPid toward its first commercial launch and draw greater attention to the technology behind its pipeline. The opportunity before that decision is to understand how those pieces could add up.
Commercial Partner Has Already Put Money Behind the Opportunity
D-PLEX100 is designed to deliver doxycycline directly into the surgical wound for about 30 days. In the Phase 3 SHIELD II study in colorectal surgery with large incisions, the product met its primary endpoint and reduced the relative risk of surgical-site infections by 60% versus standard of care on the secondary endpoint (p=0.0013).
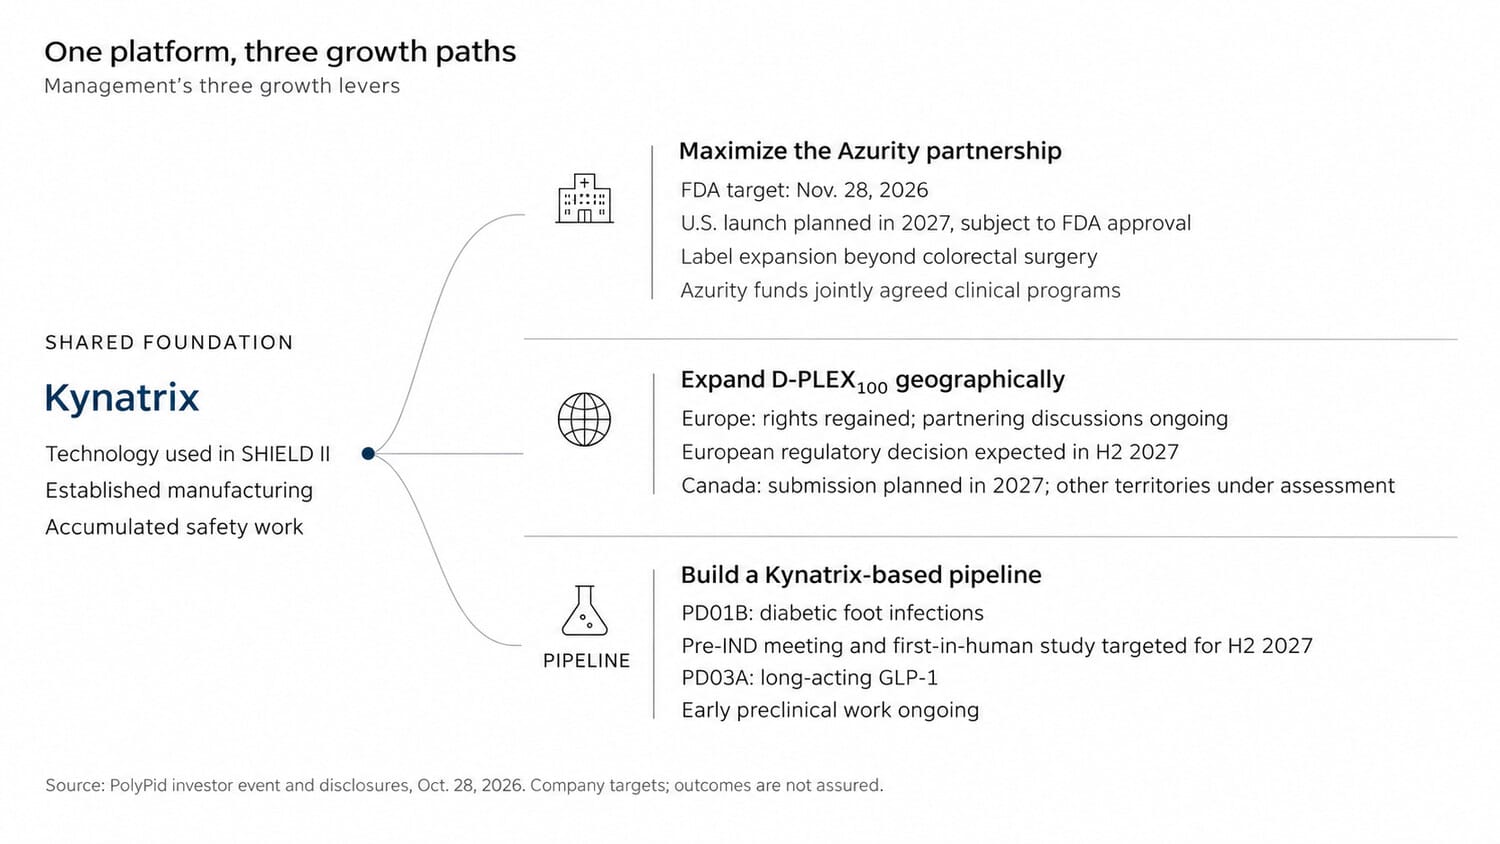
In July, PolyPid signed a U.S. and Canadian commercialization agreement with Azurity Pharmaceuticals, a global specialty pharmaceutical company. The agreement has delivered $30 million, with approximately $290 million in additional potential milestones, royalties from the mid-teens to mid-twenties, and a supply price. Milestones are contingent; royalties and manufacturing revenue offer potential ongoing income.
Management described launch preparations spanning sales, market access and medical affairs, supported by Azurity’s footprint across more than 1,700 U.S. hospitals and academic centers. A U.S. launch is expected in 2027 if approved.
Azurity will also fund clinical development for jointly agreed label expansion. That creates a route to grow beyond the initial colorectal indication while limiting the development burden on PolyPid. Approval could therefore begin a commercial business with room to expand, backed by a partner already preparing to execute.
Europe Could Come Back With Better Economics
PolyPid regained European rights in October after mutually terminating its ADVANZ PHARMA agreement. The original 2022 deal included approximately $2.6 million upfront and more than $110 million in potential upfront and milestone payments, plus royalties and a supply price.
The asset has advanced substantially since those terms were negotiated. Positive SHIELD II results are now available, the FDA application has Priority Review, and the European application is under formal review. Management said European partnership discussions were active, with an EMA decision expected in the second half of 2027.
That gives PolyPid a credible basis to seek materially stronger economics. The North American deal’s $30 million already received illustrates how its partnering position has evolved. A new European agreement could provide another payment stream alongside U.S. commercialization, with PolyPid negotiating around a more advanced asset and a recent deal template.
PD01B Makes the Platform Opportunity Tangible
PD01B aims to extend Kynatrix, PolyPid’s drug-delivery technology, into treating moderate to severe diabetic foot infections. Management estimated that 1.5 million to 1.6 million people in the U.S. live with diabetic foot infections annually. These wounds can progress to hospitalization and amputation, creating a substantial clinical and economic burden.
Poor circulation can limit antibiotic delivery into infected tissue. PD01B is designed to release high local doxycycline concentrations for weeks after damaged tissue is removed. Specialist Dr. Warren Joseph described a potential role in outpatient wound-care centers and podiatry offices, opening a different care setting from D-PLEX100’s operating-room use.
The development advantage is the foundation already in place. The investor-day presentation identified technology clinically validated in SHIELD II, a familiar antibiotic, established manufacturing and quality-control capabilities, and accumulated preclinical and safety work. Management believes these could support a potentially accelerated, more capital-efficient path into the clinic. PolyPid retains worldwide rights to PD01B.
That gives the platform argument an economic dimension: investment in the first product could support development of a second, wholly owned opportunity. Success in a new indication could expand the business while putting existing manufacturing and development capabilities to further use.
The FDA decision remains uncertain, European terms remain to be negotiated and PD01B must establish its own clinical results. Its pre-IND meeting and first-in-human study are targeted for the second half of 2027, giving the platform another concrete development milestone.
At roughly $125 million, PolyPid may still be under the radar. But with a funded commercial partnership, renewed European deal potential and a platform that could expand into other high-value indications, the company has multiple avenues for growth. A potentially transformative FDA decision, targeted for November 28, could mark the start of a much bigger story.
Recent News Highlights from PolyPid (NASDAQ: PYPD)
PolyPid to Present D-PLEX100 Microbiology Data at IDWeek 2026
PolyPid to Host Virtual Investor Day on Wednesday, October 28, 2026
European Medicines Agency Validates PolyPid’s Marketing Authorization Application for D-PLEX100
PolyPid Provides Corporate Update and Reports Second Quarter 2026 Financial Results
PolyPid Announces FDA Acceptance of NDA with Priority Review for D-PLEX100
Read this Next >>
Gilead’s Latest Deal Shows Big Pharma’s Appetite for Oral Peptides. Which Stocks Are Worth Watching?
Important Disclaimers and Disclosures: Wall Street Wire is a media and content technology platform covering capital markets and emerging public companies. PolyPid Ltd. (the "Issuer") is a paid subscriber to Wall Street Wire's Market Discovery Program, under which Wall Street Wire publishes and distributes content concerning the Issuer in exchange for an ongoing cash subscription fee. This commercial relationship creates a conflict of interest, and the coverage is not independent. Wall Street Wire is not a broker-dealer or investment adviser, and its content is provided for informational purposes only and does not constitute investment advice or a recommendation to buy or sell securities. This article may contain forward-looking statements concerning the Issuer's business and prospects that involve risks and uncertainties; actual results may differ materially. Readers should review the Issuer's public filings on SEC EDGAR (sec.gov/edgar) for applicable risk factors. References to market size estimates, valuations, price targets, or other third-party data are provided strictly for informational purposes. Market size figures, research estimates, or other third-party data referenced in this article are quoted from publicly available sources believed to be reliable; however, we do not independently verify or endorse them, and additional figures or estimates may exist. The $10 price target and "Outperform" rating referenced in this article are those of Oppenheimer and its analyst as of October 27, 2026, are noted here strictly as a statement of fact, and are not the price target, rating, or view of Wall Street Wire or of the Issuer. Neither Wall Street Wire nor the Issuer endorses them. The full report is available to Oppenheimer's clients and is subject to its own disclaimers and disclosures. Full compensation details, information about Wall Street Wire's operator, and additional disclosures are available at wallstwire.ai/disclosures. This article is not an official communication of the Issuer. Images may be computer generated and are for entertainment and visualization purposes only, and may not be an accurate or exact depiction of the technology.